
Summary
Stocks advanced this week, with the S&P 500 up +1.89%, the Dow up +1.43%, and the Nasdaq up +1.84%. September payrolls rose +29,000, missing the +90,000 estimate and slowing from August’s revised number of +133,000. Unemployment rose to 4.2%, and wage growth cooled to +0.1% on the month and +3% year over year. The ISM Services Index slippedfell to 54.9 from 55.4 as new orders lagged and prices paid rose, while employment improved to 50.1 from 47.8. Initial jobless claims edged down to 197,000 from 199,000. Minutes from the Fed’s September meeting showed most officials expect another hike by year end, with nearly all seeing upside inflation risks. Markets fully price 1 more hike by year end. SpaceX (SPCX) rose after agreeing to buy a nationwide spectrum portfolio from Grain Management to build out Starlink Mobile, sending causing T-Mobile (TMUS) and Verizon (VZ) to fall by −13% and −9%, respectively. Delta (DAL) rose despite cutting its full year outlook on roughly $6 billion in added fuel costs versus 2025. Lumentum (LITE) rose more than +5% after saying its components are sold out through early 2029. Gold rose +1.2% and silver +0.5%. Crude finished flat after President Trump said the US will not strike Iran before the midterms. The 10 year yield was unchanged at 5.24%, Bitcoin fell more than 2.5%, and the dollar rose +0.31%.
10-Year Treasury Yield
- Current Rate: 5.24% (as of October 9, 2026)
- Week-to-Date Movement: 0bps (from 5.24% on October 1, 2026)
Major U.S. Equity Indices Performance
- S&P 500: 7,666.45 → 7,811.54 (+1.89% WTD)
- Dow Jones Industrial Avg: 50,926.56 → 51,654.95 (+1.43% WTD)
- Nasdaq Composite: 26,871.60 → 27,366.17 (+1.84% WTD)
Notable Market Events
Macroeconomic Data:
September nonfarm payrolls, released last Friday, showed the US economy added +29,000 jobs. That missed the +90,000 estimate and slowed from +133,000 the prior month. The unemployment rate rose to 4.2%. Wage growth cooled to +0.1% on the month and +3% year over year. The ISM Services Index fell to 54.9 in September from 55.4. New orders lagged, and prices paid rose amid a volatile geopolitical backdrop. Employment was the outlier, climbing back above 50 to 50.1 from 47.8. MBA mortgage applications came in at −4.2% for the week ending October 2 as rates moved modestly higher. Initial jobless claims edged down to 197,000 for the week ending October 3 from 199,000 the prior week.
Economic Policy:
Minutes from the Fed’s September meeting showed most officials expect another rate hike by year end. All 19 officials backed the September hike. Nearly all see inflation risks tilted to the upside, and some warned AI could push demand above supply and lift inflation. As of Thursday’s close, markets fully priced in 1 more hike by year end.
Business:
Three moves stood out this week. 1) SpaceX (SPCX) rose slightly on Friday after agreeing to acquire a nationwide low band spectrum portfolio from Grain Management to establish Starlink Mobile as a major US carrier. The deal rippled across telecom, with T-Mobile (TMUS) and Verizon (VZ) posting −13% and −9%, respectively. 2) Delta (DAL) rose slightly on Friday despite cutting its full year earnings outlook on elevated jet fuel prices. The airline expects to absorb about $6 billion in additional fuel costs this year compared with 2025. 3) Lumentum (LITE) rose more than +5% after the optical equipment maker said its components are sold out through early 2029 on demand from tech companies racing to build faster AI data centers.
Markets:
Commodities finished the week mostly higher. Precious metals advanced slightly, as spot gold and silver rose +1.2% and +0.50% respectively. Crude oil finished the week flat as President Donald Trump announced that the US will not launch military strikes against Iran before midterms. Bitcoin fell over -2.5%, while the dollar rose +0.31%.
Stock Sector Performance
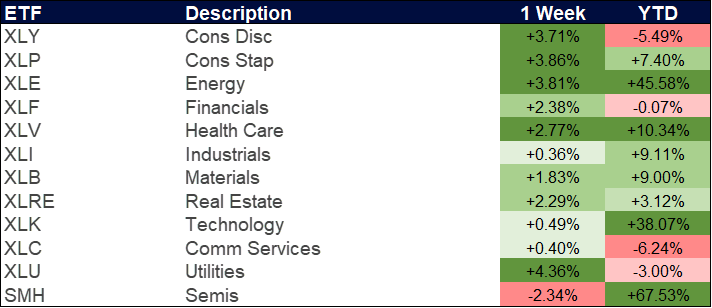
All performance figures and market events are sourced from Bloomberg as of market close 10/9/2026, using the prior Friday’s market open as the start date.

5404 Wisconsin Ave., Suite 330, Chevy Chase MD, 20815
(301) 799-9001
General Disclosure
This Presentation is for informational purposes only and does not constitute an offer to sell or the solicitation of an offer to purchase any security or investment product or services. The content of this Presentation is provided solely for your personal use and shall not be deemed to provide access to any particular transaction or investment opportunity.
This investment strategy is based on a model portfolio developed by Dynasty Wealth Management, LLC (“Model provider”), a registered investment adviser with the Securities and Exchange Commission. TritonPoint Partners retains full discretion over the implementation, customization, and management of client accounts using this model. The Model provider does not manage client accounts, does not provide individualized investment advice, and is not responsible for investment decisions, performance outcomes, or suitability determinations. The Model provider receives compensation from the underlying investments. Outsourcing costs range from 2 – 4 bps (program fee) and can be discounted based on assets under management. Outsourcing includes investment management, trading, billing, and communications.
TritonPoint Partners (TPP) does not intend the information in this Presentation to be investment advice, and the information presented in this Presentation should not be relied upon to make an investment decision. Any third-party information contained herein was prepared by sources deemed to be reliable but is not guaranteed.
TPP is a registered investment adviser with the Securities and Exchange Commission providing investment advisory and financial planning services. Any reference to the terms “registered investment adviser” or “registered” does not imply that TPW or any person associated with TritonPoint Partners has achieved a certain level of skill or training. A copy of TPP’s current written disclosure (ADV 2A Firm Brochure) discussing our advisory services and fees is available for your review upon request. TPP, in addition to providing investment advisory and financial planning services, provides business consulting services. In connection with its business consulting services, TPP does not provide tax or legal advice.
This material is proprietary and may not be reproduced, transferred, modified, or distributed in any form without prior written permission from TPP. TPP reserves the right, at any time and without notice, to amend, or cease publication of the information contained herein. Certain of the information contained herein has been obtained from third-party sources and has not been independently verified. It is made available on an “as is” basis without warranty. Any recommendations, projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.